For many independent professionals, the single greatest financial hurdle is not necessarily earning too little, but rather managing the unpredictable timing of cash flow. A completed project can be invoiced immediately, yet payment might remain weeks away. Similarly, a quiet period between contracts can create an immediate financial crunch as personal bills continue to arrive on a regular schedule.
This inherent mismatch does not mean an individual’s business model is failing; rather, it highlights a structural challenge where money simply arrives at the wrong time. While a personal loan can help cover a specific personal expense during these cash flow gaps, financial advisors emphasize that borrowing should never become a routine mechanism for managing irregular income.
The structure of the repayment plan matters significantly. Personal installment loans divide what is owed into predictable, scheduled payments over time, offering a distinct alternative to high-interest payday loans that typically demand a lump-sum repayment around the borrower’s next payday. For freelancers who lack a traditional, fixed payday, this structural difference is particularly vital for maintaining long-term financial stability.
How Do Installment Loans Compare to Payday Loans for Freelancers?
Installment loans rely on scheduled payments over a defined term, whereas payday loans generally require a full lump-sum repayment around the borrower’s next paycheck. For self-employed individuals operating without a standard pay schedule, that distinction is crucial.

Fixed monthly payments provide a clearer, more manageable framework when freelance income arrives at uneven intervals. Understanding how personal installment loans function makes it easier to compare their fixed repayment structures with high-cost payday borrowing, which often carries staggering annual percentage rates.
Some installment products offer repayment terms extending up to 24 months, providing borrowers with an extended window to spread out costs. However, financial experts caution that a longer schedule does not automatically make borrowing more affordable. Freelancers must still carefully evaluate whether each monthly payment comfortably fits within their variable income stream.
The Top Installment Loan Options for Freelancers
Loan amounts, repayment terms, funding speeds, and eligibility criteria vary significantly across different lenders. Examining several prominent options reveals how alternative installment loan structures operate for independent professionals.
CreditNinja functions as a state-licensed online lender providing personal installment loans up to $5,000, featuring transparent terms and flexible repayment options. Designed with fixed monthly payments, these loans offer a structured alternative to predatory payday and title loans. Depending on the borrower’s state and qualifications, repayment terms can stretch up to 24 months. Utilizing technology-driven underwriting through a secure online platform, the direct lender reviews overall income and the ability to repay rather than relying solely on traditional credit scores. With same-day or next-day funding capabilities, the product often addresses time-sensitive personal expenses during delayed client payments.
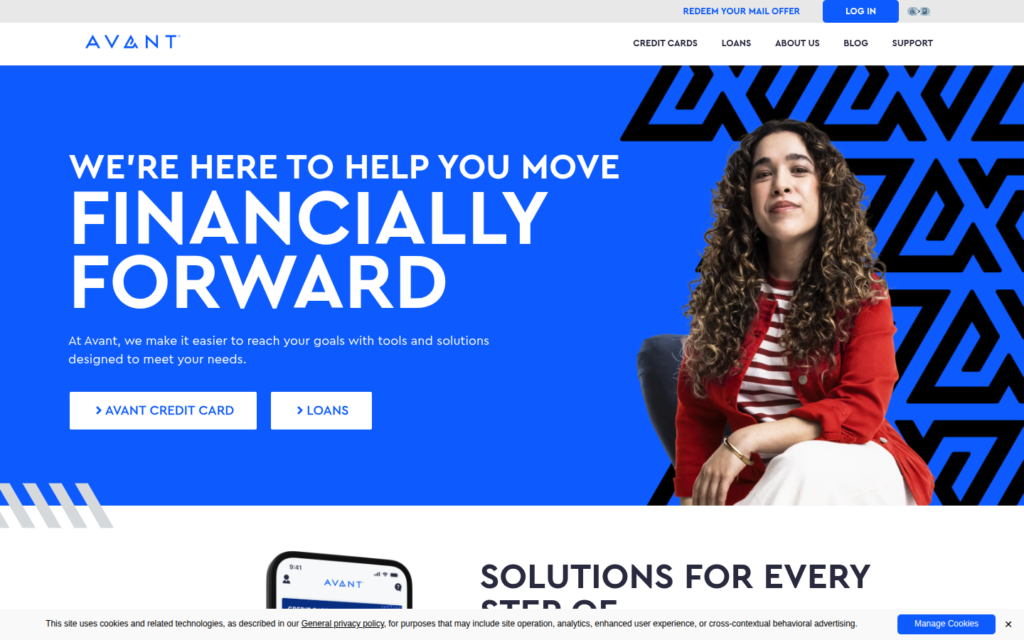
Avant offers online personal loans ranging from $2,000 to $35,000, with available amounts fluctuating by state. Repayment terms span from 24 to 60 months, giving borrowers multiple ways to spread scheduled payments over an extended period. Funding can arrive as quickly as the next business day following application approval. Primarily serving fair-credit borrowers, the platform also provides financial wellness resources, though applicants must account for administrative fees that can reduce the initial loan proceeds.
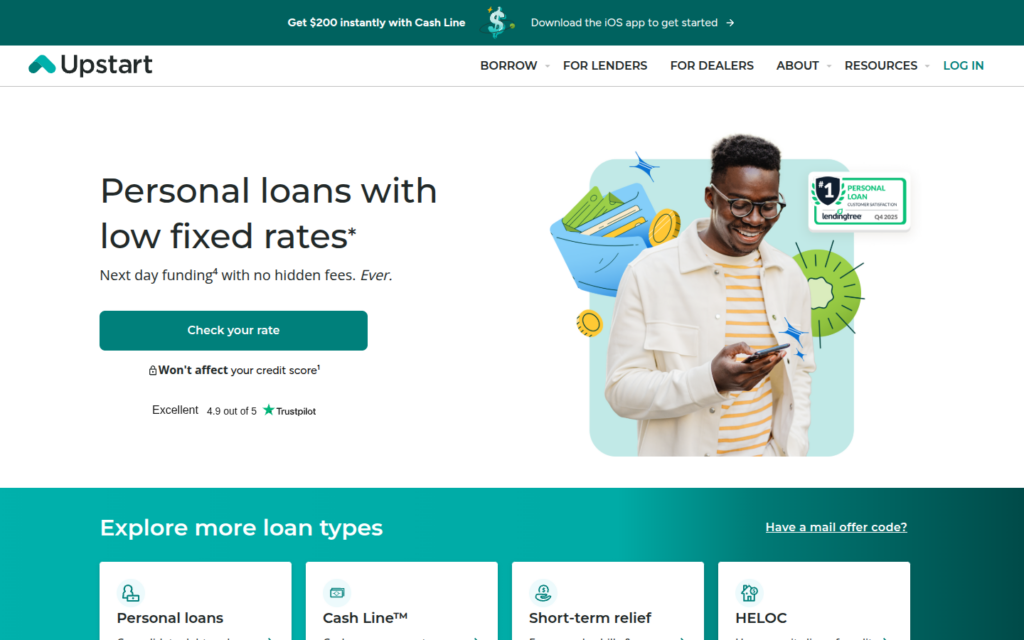
Upstart operates as an AI-powered lending marketplace connecting applicants with partner financial institutions. Its alternative underwriting approach evaluates data beyond conventional credit scores, accommodating borrowers with thinner credit files. Personal loan amounts span from $1,000 to $75,000, with repayment terms set at either 36 or 60 months. While the platform does not charge prepayment penalties, origination fees can impact the final loan amount received.
OneMain Financial bridges online lending services with a traditional network of physical brick-and-mortar branches. Personal loans typically range from $1,500 to $30,000, offering terms of 24, 36, 48, or 60 months. Funding is typically disbursed within one to two business days. The presence of physical branches gives applicants the opportunity to discuss their financial situation in person, though borrowers must weigh the commitments of a multi-year repayment schedule against their immediate needs.
Xact provides smaller personal installment loans ranging from $500 to $5,000, with repayment periods extending up to 18 months. Funding can be secured by the next business day upon approval. While the lower loan limits suit borrowers who do not require large sums, rates and terms vary widely depending on state regulations and individual borrower profiles.
How These Installment Loans Compare
Evaluating borrowing options requires looking beyond maximum loan amounts. Term lengths, funding speeds, fee structures, and potential drawbacks are equally critical when managing irregular freelance earnings. Lenders like CreditNinja and Xact cater to smaller, shorter-term borrowing needs with rapid funding timelines, whereas institutions like Avant, Upstart, and OneMain Financial provide larger loan amounts paired with extended multi-year repayment commitments. Each option presents distinct trade-offs regarding state availability, origination fees, and credit score requirements.
Which Installment Loan Fits Different Freelancer Needs?

Selecting an appropriate installment loan involves balancing multiple factors, including funding speed, credit profile, and repayment architecture. For independent contractors seeking smaller amounts with rapid turnaround times, options like CreditNinja provide accessible online solutions with fixed payments, easing cash flow crunches when traditional bank financing is unavailable.
Borrowers prioritizing fair-credit accessibility and educational financial resources often look toward Avant, while individuals with thin credit histories may find success with Upstart’s artificial intelligence-driven underwriting models. Meanwhile, self-employed workers who prefer in-person consultations can utilize lenders with physical branch networks, such as OneMain Financial.
Regardless of the chosen provider, evaluating monthly obligations, term lengths, and associated fees remains essential for anyone navigating variable monthly revenue.
What Should Freelancers Consider Before Borrowing to Cover an Income Gap?
Before committing to any loan agreement, independent professionals must calculate the exact amount required, assess when their business income is reasonably expected to recover, and determine whether scheduled monthly payments would remain manageable if client invoices experience further delays.
When income fluctuations become a regular, predictable part of business cycles, recurring personal installment loans may not be the ideal solution. Financial experts often suggest that seasonal revenue swings are better managed through dedicated business financial tools, such as professional lines of credit, rather than repeatedly relying on personal credit products.

Bridging the Gap Without the Guesswork
Financial analysts generally advise starting with the repayment structure rather than focusing exclusively on how quickly funds can be deposited. While predictable monthly installments are often easier to budget for than lump-sum payday obligations, a structured schedule does not automatically render a loan affordable.
Loan amounts, monthly commitments, repayment periods, fees, and projected earnings must align carefully. Temporary financial gaps should ideally remain isolated incidents, as compounding debt obligations can quickly complicate a freelancer’s financial foundation. Thoroughly reviewing actual loan terms and state disclosures remains the most reliable method for determining whether a specific financial product suits an individual’s professional circumstances.